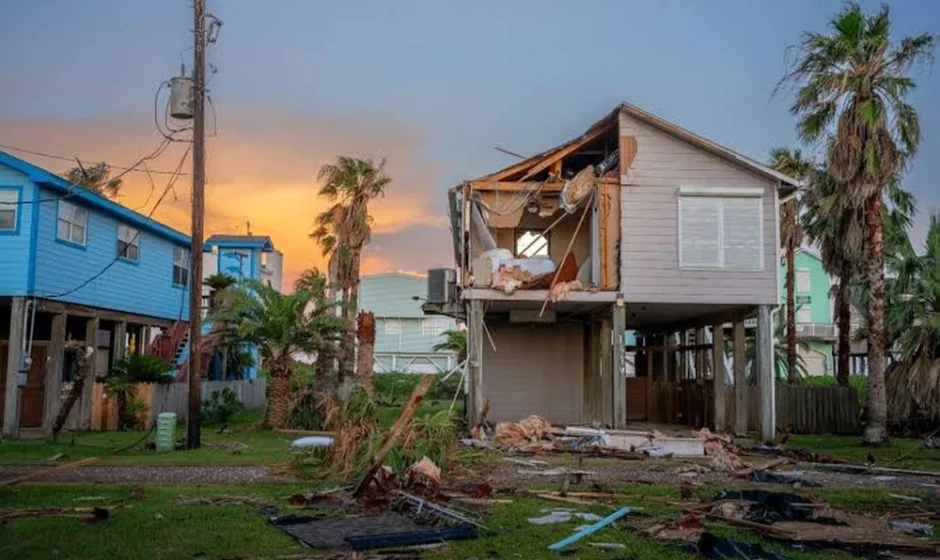

Hail in southeast Texas rarely looks dramatic from the driveway. The storm rolls through, the yard fills with snapped twigs and shredded leaves, and the roof seems fine. Then a few weeks or months later a brown ring creeps across a bedroom ceiling, and by that point the clearest proof of what caused it has been rinsed, baked and scuffed away. Roof damage has a shelf life, and the window for reading it is much shorter than most people think.
That is why homeowners around Montgomery, Conroe and Magnolia who call Cedar Rock Roofing after a bad storm tend to want two things at once. They want a free, no pressure look at the roof from a veteran-owned crew based in town, and they want someone to help document the damage properly before the insurance conversation even starts.
The Clock Starts When the Clouds Clear
Fresh hail hits on asphalt shingles show up as dark, slightly shiny spots where the granules were knocked loose and the asphalt underneath is exposed. Give those spots a few weeks of Texas sun and they oxidize, dull down and start to blend with ordinary age wear. What looked like an obvious impact on day three becomes an argument by month four.
Wind damage fades too. A shingle that lifts in a gust can partially settle back down once the afternoon heat softens the sealant strip, hiding a broken seal that will let the next sideways rain slip underneath. Debris that dented a ridge cap gets blown off. Granules that would have piled up at the bottom of a downspout wash into the lawn.
There is also a paperwork clock. Most homeowners policies set a time limit for reporting storm damage, and the further you drift from the storm date, the harder it becomes to prove which weather event did what. Checking your policy for that deadline is worth five minutes the week after any serious storm.
Where the Roof Keeps Its Receipts
Shingles are not the only witnesses. Soft metal around the house often tells a cleaner story than the roof itself, because aluminum and thin steel dent in a way that records hailstone size and even the direction the storm came from. Vent caps, ridge vents, gutters, downspouts, the fins on the AC condenser, window screens and even mailbox lids all hold that record.
On the shingles, a real hail strike usually feels soft when pressed, a little like a bruise on an apple, because the fiberglass mat underneath has fractured. Wind damage reads differently. Look for creased tabs, missing pieces, nails that have backed out and ridge caps sitting crooked.
If you want to gather your own evidence without climbing anything, this order works well from the ground up.
- Start at the downspouts and gutters, where loose granules collect in noticeable drifts after hail.
- Move to the soft metals and the AC unit, photographing dents next to a coin or tape measure so the size is clear.
- Scan each roof slope with binoculars or a phone zoom for missing tabs, lifted edges and shifted ridge caps.
- Go into the attic with a flashlight, ideally after the next rain, and look for daylight, damp decking, rusty nail tips or stained insulation.
- Finish inside the house along ceilings, around the chimney and near any skylights.
Stay off the roof itself. Wet shingles on even a moderate pitch are slicker than they look, and a fall costs far more than any claim is worth.
Telling the Storm Apart From the Calendar
This is where many claims stall. An adjuster’s job is partly to separate storm damage from normal aging, and Texas heat ages a roof quickly. Blistering, thermal cracking, curled edges and granule loss spread evenly across a whole slope usually point to time rather than weather.
Storm damage looks random by comparison. Hits are scattered, often concentrated on the slopes that faced the storm, and they show up alongside dented metal on that same side of the house. Adjusters commonly mark off a small test square on each slope and count impacts inside it, so a handful of hits spread thinly may not meet their threshold even when the roof genuinely took a beating.
An independent inspection before or alongside the adjuster visit helps here. A roofer who walked the roof the week of the storm and photographed the fresh marks gives you something to compare against the adjuster’s report line by line.
Paper Trails That Hold Up
Good documentation is boring and thorough. Take wide photos of each side of the house first, then close shots of each damaged spot, and keep the original files with their dates intact. Write down the storm date and save a local weather report or hail map that covers your street.
The Texas Department of Insurance recommends photographing and filming the damage, making a list of everything affected inside and out, and holding on to damaged items until your insurer says otherwise. It also points out that your policy may cover temporary repairs like tarping, so receipts matter. The same guidance warns homeowners that waiving a deductible is illegal under Texas law, and that a contract with blank spaces should never be signed.
Keep a running log of every call with your insurance company, including names and dates. If a claim gets disputed months later, that log is often what settles it.
Strangers With Ladders
Big storms draw crews from out of state within days. Some do fine work. The trouble is what happens in year two or three, when a pipe boot leaks or a flashing detail fails and the company that installed it has moved on to the next hail zone.
Texas does not issue a statewide roofing license, so the vetting falls on the homeowner. A few warning signs come up again and again. Door knockers who appear the morning after a storm, pressure to sign on the spot, an offer to “take care of” your deductible and a request for a large payment up front all deserve a firm no. A local physical address, proof of insurance, references from nearby jobs and a written warranty you can actually enforce are worth far more than a fast start date.
Repair or Replace Once the Facts Are In
Localized damage on a younger roof usually calls for repair. Replacing a section of shingles, resealing lifted tabs or swapping a cracked ridge cap can buy many more years.
Replacement makes more sense when hits are spread across several slopes, when the roof was already near the end of its life, or when the original shingle color has been discontinued and a patch would never match. Decking is the hidden variable. Soft or water stained plywood found during tear off adds cost, which is why a written estimate should explain how decking repairs are priced.
If you are replacing anyway, impact rated shingles tested to UL 2218 Class 4 are worth pricing out. They resist hail better than standard laminates, and many Texas insurers offer premium discounts for them, which can soften the upgrade cost over time.
The common thread in all of this is timing. A roof tells you exactly what a storm did to it, but only for a little while. Reading it early, writing it down and choosing someone who will still be around to stand behind the work turns a stressful week into a manageable one.